Cost is one of the three pillars of project success, alongside schedule and quality. A project that is delivered on time and to specification but costs far more than planned is not a success. Cost estimation and budget control are the disciplines that ensure a project is affordable, funded, and delivered within the money available.
Cost estimation is the process of predicting what a project will cost. Budget control is the process of ensuring that actual costs stay within the approved budget. Together, they determine whether the project is financially viable—and whether the owner gets what they paid for.
For small to medium-scale industrial plants, cost estimation and budget control are especially important because there is less margin for error and fewer resources to absorb cost overruns. An accurate estimate supports good decisions; a poor one leads to underfunding, delays, and disputes.
This article covers the key practices in plant cost estimation and budget control, from estimating methods to change management and cost reporting.
What Is Cost Estimation and Budget Control?
Cost estimation is the process of predicting the cost of a project or a component of a project. Budget control is the process of managing actual costs against the approved budget.
Together, they cover:
-
Estimating: Predicting costs for each element of the project.
-
Budgeting: Allocating the approved budget to work packages.
-
Commitment tracking: Tracking contracts and purchase orders.
-
Cost tracking: Tracking actual costs against budget.
-
Forecasting: Predicting final costs based on current trends.
-
Change management: Managing changes and their cost impact.
-
Reporting: Reporting cost performance to management.
Cost estimation and budget control are not just financial functions. They are project management functions that require technical knowledge as well as financial discipline.
Why Cost Estimation and Budget Control Matter
Cost performance has significant consequences.
| Factor | Impact of Good Cost Management | Impact of Poor Cost Management |
|---|---|---|
| Viability | Project remains financially viable | Project becomes unaffordable |
| Funding | Funding secured and sufficient | Funding shortfalls and delays |
| Decisions | Decisions based on accurate data | Decisions based on guesswork |
| Disputes | Fewer disputes with contractors | More disputes and claims |
| Reputation | Owner and contractor credibility | Reputation damaged |
| Completion | Project completed as planned | Project delayed or abandoned |
For small plants, where there is less margin for error, cost management determines whether the project can be completed.
Cost Estimation Methods
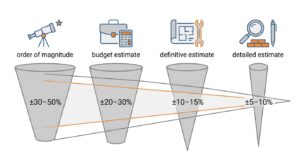
Different estimating methods are used at different stages of a project.
| Method | Description | Accuracy | When to Use |
|---|---|---|---|
| Order of magnitude | Based on capacity or similar projects | ±30% to ±50% | Concept stage |
| Budget estimate | Based on preliminary design | ±20% to ±30% | Feasibility stage |
| Definitive estimate | Based on detailed design | ±10% to ±15% | Basic engineering stage |
| Detailed estimate | Based on completed design and quotes | ±5% to ±10% | Detailed design stage |
Estimate accuracy improves as design progresses. Early estimates are used for feasibility decisions; later estimates support budget approval and contract awards.
Cost Categories
Project costs are typically divided into categories.
| Category | Description | Examples |
|---|---|---|
| Equipment | Major equipment items | Turbines, boilers, compressors |
| Bulk materials | Commodity materials | Pipe, fittings, valves, cable |
| Construction | Construction labor and services | Civil, mechanical, electrical |
| Engineering | Design and engineering services | Process, mechanical, electrical |
| Project management | Project management and administration | Salaries, offices, travel |
| Owner’s costs | Costs borne by the owner | Land, permits, insurance, financing |
| Contingency | Reserve for unknowns | Scope, price, schedule |
Each category should be estimated separately and tracked separately.
Work Breakdown Structure (WBS)
A work breakdown structure (WBS) divides the project into manageable components.
WBS principles:
-
Hierarchical: Each level breaks the level above into smaller components.
-
Complete: All project scope is included.
-
Unique: Each component has a unique identifier.
-
Manageable: Components are small enough to plan, estimate, and control.
Typical WBS levels:
| Level | Description | Example |
|---|---|---|
| 1 | Project | Power plant |
| 2 | Major systems | Boiler, turbine, electrical |
| 3 | Subsystems | Feedwater, fuel, control |
| 4 | Work packages | Pumps, valves, instruments |
| 5 | Activities | Installation tasks |
The WBS provides the framework for estimating, budgeting, and cost control.
Estimating Techniques
Several techniques are used to estimate costs.
| Technique | Description | When to Use |
|---|---|---|
| Parametric | Based on historical relationships (e.g., cost per MW) | Early stages |
| Analogous | Based on similar past projects | When data is limited |
| Bottom-up | Built from detailed quantities and rates | Detailed stages |
| Vendor quotes | Based on actual vendor pricing | For equipment and services |
| Expert judgment | Based on experience | For unusual items |
Most estimates use a combination of techniques. Equipment is often priced by vendor quotes; construction is often priced bottom-up from quantities.
Contingency
Contingency is a reserve for unknowns. It covers costs that are likely to occur but cannot be specifically identified at the time of estimating.
Types of contingency:
| Type | Description | Examples |
|---|---|---|
| Scope contingency | For scope changes | Additional work identified during design |
| Price contingency | For price changes | Material price increases |
| Schedule contingency | For schedule changes | Delays due to weather or labor |
| Management reserve | For unidentified risks | Reserved by management |
Contingency sizing:
-
Early stages: Higher contingency (e.g., 15–25%) due to uncertainty.
-
Later stages: Lower contingency (e.g., 5–10%) as uncertainty reduces.
-
Risk-based: Contingency based on quantitative risk analysis.
Contingency should be managed, not treated as free money. Drawing it down should be controlled.
Budget Development
The budget is the approved spending plan for the project.
Budget development steps:
-
Estimate: Estimate the cost of each WBS element.
-
Review: Review the estimate for completeness and accuracy.
-
Approve: Obtain approval from management or the owner.
-
Allocate: Allocate the budget to work packages and cost accounts.
-
Baseline: Establish the baseline budget for control.
The baseline budget is the reference against which actual costs are compared.
Budget Control
Budget control ensures that actual costs stay within budget.
Budget control activities:
| Activity | Description |
|---|---|
| Commitment tracking | Tracking contracts, purchase orders, and commitments |
| Cost tracking | Tracking actual costs against budget |
| Accruals | Recording costs incurred but not yet invoiced |
| Forecasting | Predicting final costs based on current trends |
| Variance analysis | Comparing actual and forecast costs against budget |
| Corrective action | Taking action when variances are significant |
Budget control requires accurate data and timely reporting.
Earned Value Management
Earned value management (EVM) integrates cost, schedule, and scope to measure project performance.
Key EVM metrics:
| Metric | Description | Formula |
|---|---|---|
| Planned Value (PV) | Budgeted cost of work scheduled | — |
| Earned Value (EV) | Budgeted cost of work performed | — |
| Actual Cost (AC) | Actual cost of work performed | — |
| Cost Variance (CV) | EV − AC | Positive = under budget |
| Schedule Variance (SV) | EV − PV | Positive = ahead of schedule |
| Cost Performance Index (CPI) | EV ÷ AC | >1 = efficient |
| Schedule Performance Index (SPI) | EV ÷ PV | >1 = ahead |
EVM provides early warning of cost and schedule problems, allowing corrective action before it is too late.
Forecasting
Forecasting predicts the final cost of the project based on current performance.
Forecasting methods:
| Method | Description | When to Use |
|---|---|---|
| Budget-based | Remaining budget for remaining work | When performance is on track |
| CPI-based | Remaining budget adjusted by CPI | When performance is off track |
| Bottom-up | Re-estimate remaining work | For significant variances |
| Management judgment | Based on experience | For unusual situations |
Forecasting should be updated regularly as the project progresses.
Change Management
Changes during a project affect cost. Managing them is critical.
Change management activities:
-
Change identification: Recognizing when a change is required.
-
Change assessment: Evaluating the impact on cost, schedule, and scope.
-
Change approval: Approving or rejecting the change.
-
Change implementation: Implementing the change.
-
Documentation: Recording the change and its cost impact.
Uncontrolled changes lead to cost overruns and disputes.
Cost Reporting
Cost reporting keeps management informed of cost performance.
Cost report contents:
-
Budget: The approved budget.
-
Commitments: Contracts and purchase orders.
-
Actual costs: Costs incurred to date.
-
Accruals: Costs incurred but not invoiced.
-
Forecast: Predicted final cost.
-
Variance: Actual and forecast vs. budget.
-
Trends: Cost performance over time.
Reports should be accurate, timely, and clear.
Cost Control in EPC Projects
EPC projects have specific cost control challenges.
EPC cost control considerations:
-
Lump-sum contracts: The contractor bears cost risk, but changes may still affect the owner.
-
Shared risk: Some contracts share cost risk between owner and contractor.
-
Owner’s costs: The owner bears costs not included in the EPC contract.
-
Interface costs: Costs at the interface between EPC and owner scope.
Cost control in EPC projects requires clear contract terms and disciplined change management.
Common Mistakes in Cost Estimation and Budget Control
Even experienced organizations make mistakes. Common ones include:
-
Optimistic estimates: Underestimating costs.
-
Incomplete scope: Missing elements that later add cost.
-
Inadequate contingency: Not enough reserve for unknowns.
-
Poor change control: Changes not tracked or approved.
-
Delayed reporting: Discovering cost overruns too late.
-
Inaccurate data: Costs not recorded accurately.
-
No forecasting: Not predicting final costs.
-
Ignoring trends: Missing early warning signs.
-
Weak commitment tracking: Not tracking contracts and purchase orders.
These mistakes are costly to correct. They are much cheaper to avoid through disciplined estimating and control.
How Japanese EPC Firms Approach Cost Estimation and Budget Control
Japanese engineering firms are known for their disciplined approach to cost management. Common characteristics include:
-
Thorough estimating: Estimates are prepared carefully, with detailed quantities and rates.
-
Conservative assumptions: Estimates are based on realistic, not optimistic, assumptions.
-
Adequate contingency: Contingency is sized to cover real uncertainty.
-
Disciplined control: Costs are tracked and reported regularly.
-
Early warning: Variances are identified and addressed early.
-
Detailed documentation: Records are complete and accurate.
-
Continuous improvement: Lessons are captured and applied.
For plant owners, this often means projects that are delivered within budget and without surprises.
How to Evaluate Cost Estimation and Budget Control Readiness
When reviewing cost estimation and budget control, ask:
| Question | Why It Matters |
|---|---|
| Is there a cost estimate? | Provides the basis for budgeting |
| Is the estimate based on adequate design information? | Determines estimate accuracy |
| Is contingency adequate? | Covers unknowns |
| Is there a baseline budget? | Provides the reference for control |
| Are commitments tracked? | Ensures all costs are captured |
| Is cost tracked against budget? | Identifies variances |
| Is forecasting performed? | Predicts final costs |
| Is change management disciplined? | Prevents uncontrolled cost growth |
| Is reporting timely? | Enables early corrective action |
A plant that addresses these questions is ready for effective cost management.
Conclusion
Cost estimation and budget control are critical to project success. For small to medium-scale industrial plants, they determine whether the project is affordable, funded, and delivered within the money available.
By focusing on estimating methods, WBS, contingency, budget development, budget control, earned value, forecasting, and change management, owners and project teams can ensure that costs are managed effectively and the project is delivered within budget.